eVTOL
What Is eVTOL? The Complete Guide to Electric Air Taxis
What eVTOL means, how electric air taxis work, which companies are still standing after the 2026 shakeout, and when passengers will actually ride one.
Updated
13 news articles on eVTOL ↓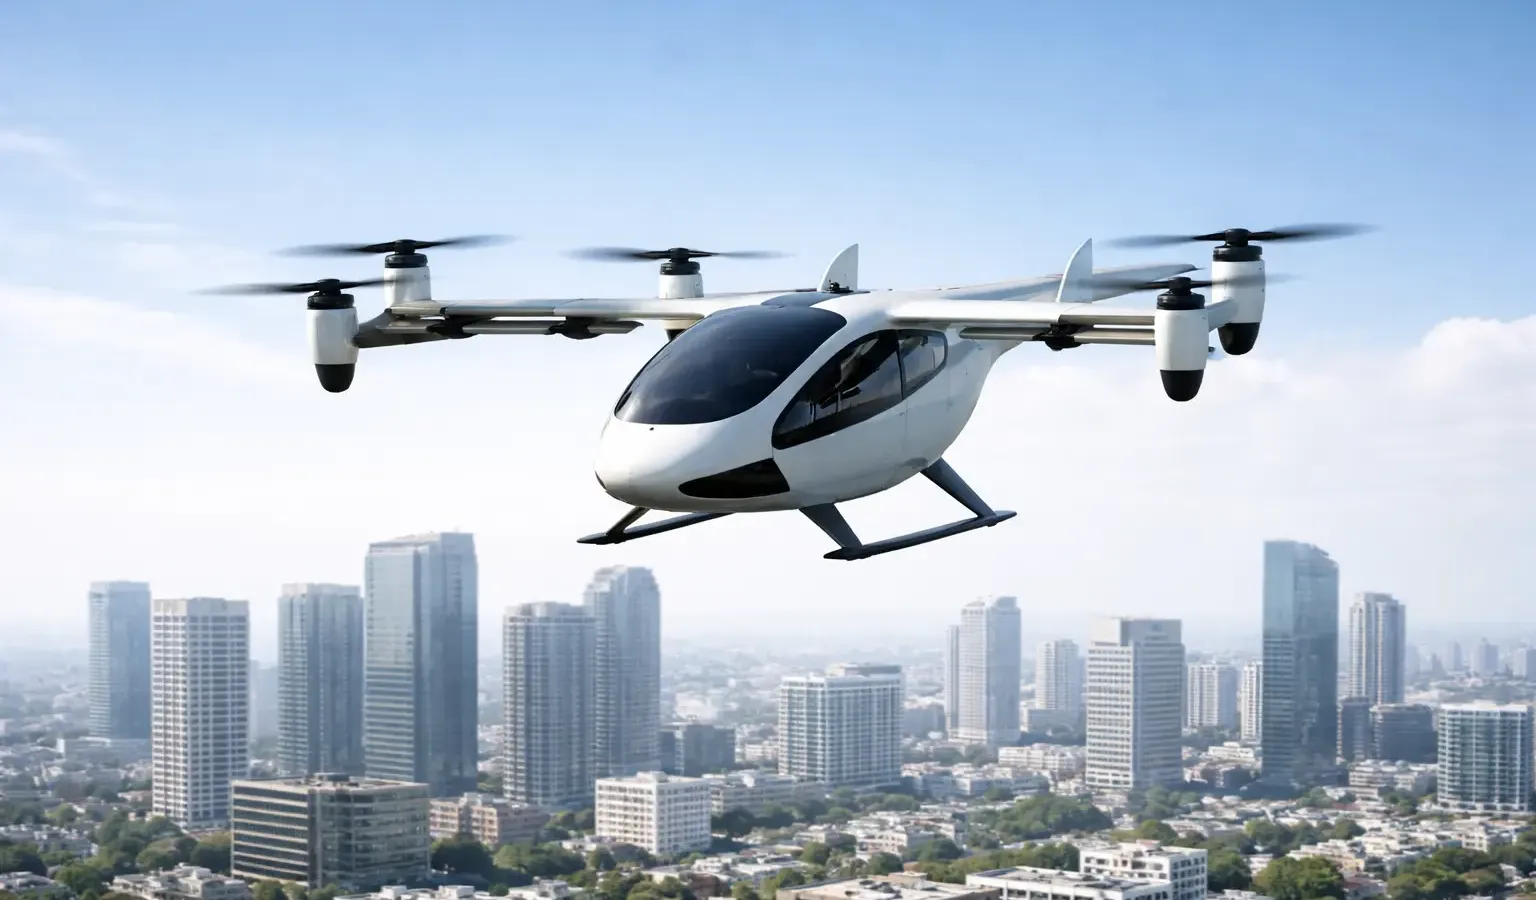
Guide
eVTOL stands for electric vertical takeoff and landing. These are battery-powered aircraft that take off and land vertically like helicopters. Instead of combustion engines, they use distributed electric motors. 2026 was the year the industry had promised its first commercial passenger service.
With less than three months left, no eVTOL manufacturer has an FAA type certificate. No Western operator has flown a paying passenger. The two programmes closest to service are launching in Dubai and Abu Dhabi, not the United States.
The technology is not what failed. The aircraft fly, they transition and they are quiet. One of them has carried passengers commercially in China for two years.
The timelines failed, and 2026 was the year the gap became impossible to paper over. Three well-funded programmes shrank, paused or changed owner during it.
This guide explains how the technology works. It then goes through who is still in the race and what each of them can honestly claim.
Key facts
- No eVTOL manufacturer holds an FAA type certificate as of mid-October 2026, and no Western operator has flown a paying passenger. EHang’s EH216 has carried passengers on sightseeing routes in China for two years.
- Joby is working through the last two of five stages of FAA certification, with five aircraft flying and FAA test pilots still to fly the conforming aircraft; Archer has had all 797 of its means of compliance accepted. Beta’s runway-launched CX300 is 89 percent through certification planning and targets a certificate by the end of 2026.
- The first Western commercial flights are set for the Gulf: Joby under a six-year exclusive with Dubai’s RTA, Archer as the first entrant to Abu Dhabi’s restricted type certificate programme. Neither had launched by mid-October 2026.
- In the United States, the FAA’s eVTOL Integration Pilot Program selected eight projects across 26 states in March 2026, and trial flights have run since July in Virginia, Utah, Louisiana, Texas and North Carolina. Full commercial passenger service, which needs a Part 135 certificate and type-rated pilots on top of a type certificate, realistically lands in 2028 or later.
- Three programmes shrank, paused or changed owner in 2026: Supernal cut about 80 percent of its staff, Volocopter re-emerged under Diamond Aircraft after insolvency, and Boeing agreed to sell Wisk to Archer.
- Joby’s S4 measures 45.2 dBA at 500 metres in cruise against 87 dBA or more for a comparable helicopter; first-generation fares are indicated at $3 to $5 a passenger-mile.
How Does eVTOL Work?
An eVTOL differs from a helicopter in how power reaches the rotors, not in its ability to hover. A helicopter uses a combustion engine to drive one large main rotor. Power runs through a complex transmission of gearboxes, shafts and a swashplate that controls blade pitch. An eVTOL sends power by wire to several independent motors, each spinning its own rotor or propeller.
There are no gearboxes, no swashplates and no tail rotor. That change has knock-on effects. Electric motors give instant torque and respond in milliseconds. So software can steady the aircraft by varying each motor’s speed, not the blade pitch.
If a single motor fails, the others compensate. The redundancy is built into the design, not bolted on. Fewer moving parts mean much less maintenance. And many small rotors, instead of one large one, sharply cut the blade-vortex interaction that makes helicopters so loud.
Noise is one of the biggest practical advantages. Joby’s S4 measures 45.2 dBA at 500 metres in cruise. That is barely perceptible against urban background noise. It stays under 65 dBA during takeoff and landing.
A comparable helicopter produces 87 dBA or more at similar distances. The human ear hears a 20 dBA reduction as roughly four to six times quieter. Noise is the main community objection to helicopter routes in cities. For urban flights, it counts as much as the emissions story.
What Are the Different eVTOL Configurations?
Three distinct aircraft designs have emerged: multirotor, lift plus cruise and vectored thrust. Each makes a different trade between simplicity, range and efficiency.
Multirotor
The simplest design uses several fixed vertical rotors in every phase of flight: hover, transition and cruise. It is steered entirely by changing the speed of individual rotors. Volocopter’s VoloCity and EHang’s EH216 are multirotor designs.
The advantage is mechanical simplicity and the most redundancy. Losing one of twelve or eighteen rotors has little effect on flight. The weakness is drag in cruise, because vertical rotors resist the air when the aircraft flies forward. Practical range is typically 20 to 40 kilometres — enough for short city hops but not for real route networks.
This is the only design that has been certified anywhere in the world and carried commercial passengers. Simplicity turned out to be worth something.
Lift Plus Cruise
This design uses dedicated vertical rotors for takeoff and hover. Separate forward-facing propellers and fixed wings take over in cruise. Once the aircraft moves into forward flight, the lift rotors are switched off or folded. The wings then provide most of the lift and the cruise propeller provides thrust.
Eve’s aircraft and Beta’s A250 use this approach. The advantage is that each propulsion system is tuned for its own flight phase. The cost is that the lift rotors become dead weight and drag in cruise. Range is much better than a multirotor’s, but two systems add weight and complexity.
Vectored Thrust
Vectored thrust designs use rotors or propeller nacelles that tilt from vertical to horizontal. The same system drives the aircraft in every phase of flight. Joby’s S4 uses six tilting propellers: two on each wing and two on the tail. They point upward for takeoff and rotate forward for cruise.
Archer’s Midnight and Vertical’s Valo use similar layouts. This approach is the most efficient across both hover and cruise. It makes possible the 100-mile range targets that city-scale air taxi networks need. The cost is complex tilting mechanisms and the hardest certification path of the three.
What Is Limiting eVTOL Range and Payload?
Battery energy density is the constraint that binds the whole industry. Current production lithium-ion packs deliver about 250 to 300 Wh/kg at the pack level. That is after safety and thermal management overhead. It limits practical passenger range to 50 to 150 miles depending on design, with reserves required for instrument flight rules.
The battery problem is harder for eVTOL than for electric cars. Hover demands very high discharge rates, roughly 2.5 to 4.5C during vertical flight. That makes heat and wears out cells faster. Cruise is far gentler at 0.75 to 1.5C, but the transition pushes demand back up.
Thermal systems must manage the whole cycle. They add weight and use up part of the energy budget.
The industry puts the threshold for commercial viability at scale at about 400 Wh/kg at the cell level. Several makers are testing solid-state and lithium-metal cells that target 500 Wh/kg. Production-ready cells could arrive by 2028 to 2030. Until then, eVTOL range and payload stay limited.
Current designs typically carry 500 to 1,000 pounds of useful load. That is enough for four passengers and luggage. A medium helicopter can carry 3,000-plus pounds.
This is the quiet reason the sector’s economics are so hard. An aircraft that carries four passengers 50 miles cannot spread its fixed costs like one carrying nine passengers 250 miles can. No certification progress changes that until the cells improve.
What Is a Vertiport and What Does One Cost?
A vertiport is the ground infrastructure for eVTOL operations. It is a purpose-built landing and takeoff site with charging, passenger handling and maintenance. It needs a pad sized to the aircraft plus clearance margins.
Each pad needs high-voltage charging of 1 to 2 megawatts to recharge a depleted pack in 30 to 60 minutes. The site also needs passenger terminal space and maintenance facilities.
Cost varies enormously with site and scale. A minimal vertiport fitted into an existing helipad or parking structure costs $1 to $5 million. A purpose-built full facility handling 500-plus daily operations costs $30 to $50 million or more.
Joby and Skyports are building vertiports in Dubai at roughly $10 million per site. The first is near Dubai International Airport. Further sites are planned at Dubai Mall, Atlantis The Royal and the American University in Dubai.
The industry underestimated grid access. A busy vertiport drawing 5 to 10 megawatts needs utility-grade power that many city sites do not have. Grid upgrades commonly take 18 to 36 months from approval to energisation. An aircraft can be certified while the places it needs to land are years behind it.
Which eVTOL Companies Are Closest to Certification?
Joby Aviation
Joby is the most technically advanced Western eVTOL programme by most measurable criteria. Its S4 carries a pilot plus four passengers at 200 mph over a 100-mile range. It measures 45.2 dBA at 500 metres in cruise.
Joby has reached stage five of five in the FAA’s powered-lift type certification process: the type certificate itself. It is working the stages in parallel: its August quarterly filing put it about 75% through the fourth stage, with “steady progress” in the fifth. Five aircraft are flying, including the first built to the FAA-conforming design, and twelve more are in production. What remains is for-credit flight testing with FAA test pilots at the controls. Those flights must show compliance with the outstanding airworthiness standards, and then comes the final administrative decision.
This is genuinely the last gate. But “last gate” has described Joby’s position for longer than the company would like.
Joby has far more money than any competitor. At the end of June 2026, it had $2.3 billion in cash, equivalents and marketable securities. It guided second-half cash use of $385 to $415 million. Toyota has committed roughly $900 million.
Second-quarter revenue was $38.6 million and full-year guidance is $115 to $125 million. But that revenue comes from the Blade passenger business Joby bought in 2025, which flies helicopters. It is not eVTOL revenue.
In Dubai, Joby holds a six-year exclusive with the Road and Transport Authority. It has completed piloted test flights there with full transitions, and the first vertiport, at Dubai International Airport, was certified by the UAE’s civil aviation authority on 7 July 2026. Joby still says it will carry its first passengers in 2026; service had not begun by mid-October.
In the United States, Joby flew its first trials under the FAA’s pilot programme around Dallas-Fort Worth from 10 to 14 September. Separately, a Cessna Caravan converted with its autonomy system flew across the country without a pilot flying it, landing in North Carolina on 18 September.
Archer Aviation
Archer’s Midnight uses a similar vectored-thrust design. It carries a pilot plus four passengers at roughly 150 mph over a 100-mile range, at about 45 dBA. Archer was the first eVTOL company to have 100% of its Means of Compliance accepted by the FAA: all 797 of them. So the agency has approved every method Archer proposed for proving the aircraft meets each safety requirement.
Archer’s bigger 2026 story is that it stopped being only an eVTOL company. In August it agreed to acquire Wisk Aero, Insitu and SkyGrid from Boeing. Boeing takes payment in shares: 19.75% of Archer’s Class A stock and options to buy more over four years. Boeing has also committed to invest up to a further $55 million before March 2027, and keeps the right to use Wisk’s autonomous flight technology in its own programmes.
The deal is expected to close by the end of 2026 and has not closed yet. The US antitrust waiting period ended on 18 September; other regulatory approvals are still pending.
If it does, Archer gains an autonomy programme, an established military drone maker in Insitu, and airspace management software. That turns a single-product air taxi company into a diversified aerospace business. It also gives Archer revenue that does not depend on certifying Midnight.
Archer has less financial room than Joby. It had $1.56 billion of cash and short-term investments at the end of June, after a second-quarter net loss of $263.2 million, and guides to a third-quarter adjusted EBITDA loss of $170 to $200 million. It holds a $142 million US Air Force contract and a United Airlines order for 200 Midnight aircraft. It is also in court against both Joby, which accuses it of taking trade secrets, and Vertical Aerospace, which countersued it for patent infringement on 6 October.
In Abu Dhabi, Archer is the first manufacturer admitted to the UAE’s Restricted Type Certificate programme, which it entered in May 2026; admission is not a certificate. It has flown a full envelope test campaign in country and targets service in 2026, and its August filing says it is on track to deliver more aircraft there this year in preparation for passenger operations. At home, it began piloted flights between Salinas, Hollister and Monterey in California on 8 September.
Beta Technologies
Beta took a different route, and it is looking like the better one. Its lead certification programme, the ALIA CX300, is a conventional takeoff and landing electric aeroplane. It uses a runway, not a vertiport. The vertical-lift variant, the A250, follows behind it.
Beta had three reasons. Fixed-wing certification is a known process. Cargo and medical missions need no new infrastructure. And the economics work better at longer range.
Certification planning for the CX300 is 89% complete, and the FAA has accepted the aircraft’s full set of compliance requirements. Beta targets certification by the end of 2026. If it lands, it will be the first certified electric aircraft of this generation. It will come from the company that deliberately skipped the vertical takeoff.
Beta listed on the NYSE in November 2025 at $34 a share, raising about $1.1 billion net. Full-year 2025 revenue was $35.6 million against a net loss of $745.9 million. Second-quarter 2026 revenue was $14.7 million, up 146%. Full-year guidance is $42 to $50 million, and cash was $1.48 billion at the end of June.
Backlog was reported at 1,001 aircraft and $3.9 billion. The shares trade well below the IPO price.
Beta also builds the charging hardware, Charge Cubes and thermal management units, and sells them as products in their own right. Service revenue, including charging and training, is currently its larger revenue line.
Its runway-launched ALIA has been busy in the FAA’s pilot programme: organ transport from Virginia to Maryland in July, then rural-healthcare flights in North Carolina from mid-September and radiopharmaceutical-delivery trials in Utah that finished on 7 October.
In July 2026 it launched the MV250, an autonomous hybrid-electric VTOL for military logistics. It was developed with GE Aerospace, and Sikorsky is integrating its MATRIX autonomy suite.
EHang
EHang remains the only company in the world whose aircraft holds a full set of civil aviation certificates for commercial passenger operations. The EH216-S has a type certificate, production certificate and standard airworthiness certificate from China’s CAAC. EHang also holds an air operator certificate. It delivered 35 EH216-series units in the second quarter of 2026 alone.
The commercial reality is more modest than the certificates suggest. Revenue was RMB25.7 million in the first quarter and RMB77.9 million in the second. Full-year guidance is RMB600 million. Operations are sightseeing and tourist routes rather than transport.
The share price has fallen roughly 79% from its 52-week high. The market capitalisation was about $300 million on 12 October. Goldman Sachs, JPMorgan and Bank of America have all downgraded the stock.
EHang proves the autonomous multirotor model works and that a regulator will certify it. Its Chinese certification does not transfer to FAA or EASA jurisdiction. And as a Chinese company listed in New York, it carries delisting risk under the HFCAA.
Volocopter
Volocopter’s position changed completely, and most descriptions of it have not caught up. The company filed for insolvency in December 2024 after failing to fly at the Paris Olympics. In March 2025 China’s Wanfeng Auto Holding Group bought its assets through its Austrian subsidiary Diamond Aircraft. The deal was reported at around €10 million, against assets valued near €42 million.
Just over 180 of roughly 500 employees were retained. It now trades as Volocopter Technologies inside Diamond Aircraft.
The certification work survived the ownership change, but the product did not. VoloCity had completed around three quarters of EASA’s certification requirements before the insolvency. The company holds both design and production organisation approvals. Type certification for it is now expected in 2027.
Volocopter is actually certifying something else first. In April 2026 it launched the VoloXPro, a two-seat electric multicopter for flight schools, flying clubs, air sports and sightseeing operators. It has 18 rotors, 40 km range, 70 km/h cruise and 600 kg maximum takeoff weight. It reuses VoloCity components, which is how the engineering survives.
The VoloXPro is going through the German ultralight category, not EASA type certification. Approval and market entry are targeted for the end of 2026.
This is widely misreported, including in an earlier version of this guide. The end-2026 date belongs to an ultralight for hobbyists, not to a certified air taxi.
Volocopter may well be the first company here to put a certified electric aircraft in customers’ hands. It would do so from the weakest starting position of any of them. But it will not be the aircraft it raised €590 million to build.
Wisk Aero
Wisk is pursuing the hardest regulatory path in the industry: fully autonomous passenger flights with no pilot on board. In December 2025 its Generation 6 aircraft first flew. Wisk supports the FAA’s eIPP with a Texas focus, specifically to gather autonomy data, and in August broke ground on a relocatable vertiport at Hollister, California, meant for that Texas testing.
Wisk was wholly owned by Boeing, a parent with effectively unlimited patience. Under the announced sale it becomes part of Archer. Archer is a pre-revenue listed company with its own piloted aircraft to certify first.
The open question is whether Archer keeps an expensive, slower autonomous programme going alongside Midnight. The answer reaches beyond Wisk. It is the only well-funded Western attempt at certifying pilotless passenger flight, and FAA rules for that do not exist in final form. Commercial autonomous service remains a post-2030 proposition.
Eve Air Mobility
Eve is backed by Embraer and listed on the NYSE as EVEX. It is developing a lift-plus-cruise aircraft for four passengers plus a pilot. It completed the first low-speed hover test of its full-scale prototype in December 2025, had flown 58 flight tests by early summer 2026, and reported its first transition flight in August 2026.
Eve pushed its certification and entry-into-service target to 2028. It had already moved it from 2026 to 2027. The conforming prototype’s first crewed flight is not expected until the second half of 2027. European certification is expected 12 to 15 months after Brazilian and US approvals.
The order book needs careful reading. Eve reports a pre-order backlog of roughly 2,700 aircraft valued at $13.5 billion. But only about 100 of those are firm orders: 50 from Revo, announced at the 2025 Paris Air Show, and 50 from AirX in February 2026. The rest are letters of intent.
Second-quarter 2026 showed a net loss of $34.2 million and cash consumption of $49.4 million. Eve had $403.3 million of cash and investments, against total liquidity of $531.3 million including BNDES credit lines.
Vertical Aerospace
Vertical retired the VX4 name in December 2025. The certification-intent production aircraft is the Valo, with an updated airframe, wing and propeller architecture. It targets four passengers over 100 miles and UK type certification in 2029. The first aircraft built to certification standard is due to start assembly in the fourth quarter of 2027.
In April 2026 Vertical closed a financing package of up to $850 million with Mudrick Capital Management and Yorkville Advisors. It is meant to cover an estimated $700 million cost of certifying Valo. That headline is not what it appears.
Vertical had about $134 million of cash in August, which it says lasts into August 2027, against about $150 million of planned spending over twelve months. The market capitalisation was about $85 million on 12 October, with a share price near $0.50. A facility of up to $850 million drawn against a company worth $85 million has equity-linked portions that severely dilute existing shareholders. That is a large part of why the shares are where they are.
The engineering is real. Vertical flew for five consecutive days at Farnborough, opened a Valo assembly centre at Cotswold Airport on 25 September, and expects a Critical Design Review by the end of 2026. It is also weighing its options: on 24 September it hired Jefferies to review “strategic alternatives”, and on 2 October it disclosed a New York Stock Exchange warning after its shares averaged under $1 for 30 trading days. It is the only European developer with a full-scale programme still running under its own name. Whether it reaches 2029 with equity value intact is a separate question from whether the aircraft flies.
Supernal
Hyundai’s eVTOL programme has effectively stopped, and the S-A2 is no longer the product.
Development was paused in late summer 2025 after the CEO and CTO both left. In late February 2026 Supernal laid off 296 people, roughly 80% of staff, across Irvine, Fremont and the Mojave Air & Space Port. That left a core team of 70 to 80. It has had no permanent CEO since.
In May 2026 Hyundai and Korea Aerospace Industries signed a memorandum of understanding to develop an advanced air mobility aircraft together. Supernal is design authority and technical lead. KAI provides airframe manufacturing and certification experience.
Supernal says the S-A2 will be used to “refine our proprietary design guides” as it moves toward a next-generation aircraft. No timeline, funding figure or hiring commitment was disclosed. The original 2028 commercial target has no announced replacement.
Anyone still reading that Hyundai has committed $1.5 billion to an aircraft entering service in 2028 is reading a 2024 press release.
Lilium
Lilium filed for insolvency for the second time in February 2025. A €200 million rescue package had failed and the German government had declined loan guarantees. Its ducted-fan design was technically distinctive but hugely capital-intensive.
In October 2025 Archer acquired roughly 300 Lilium patents for €18 million. They cover high-voltage systems, batteries and flight controls. No successor is developing the original design, and the equity has no value.
How Does FAA Certification Work for eVTOL?
The FAA created a new powered-lift aircraft category specifically for eVTOL. It operates under Part 21.17(b) as a special class. It blends requirements from Part 23 small aircraft rules, Part 25 transport category rules and rotorcraft standards. Existing categories did not fit aircraft that take off vertically, switch to horizontal flight on tilting rotors and run on distributed electric propulsion.
A type certificate proves, through ground and flight testing, that the aircraft design meets all applicable safety standards. The process has five stages, and Joby is in the fifth.
Type Inspection Authorization is the point at which FAA test pilots fly conforming, production-representative aircraft. This for-credit testing produces the evidence the certification decision rests on.
Means of Compliance are the specific test methods a manufacturer proposes to show each requirement is met. Archer’s 100% acceptance means the FAA approved every one of its 797 proposed methods. That is a design-freeze milestone, showing the compliance plan is complete.
A type certificate alone is not enough to fly paying passengers. Operators also need a Part 135 Air Carrier Certificate. Pilots need type ratings specific to the aircraft.
Operations manuals, maintenance programmes and vertiport approvals run as separate processes. The full stack adds 12 to 24 months beyond the type certificate date. Most public timelines quietly leave this step out.
EASA’s equivalent pathway is Special Condition VTOL. FAA and EASA have reciprocal validation agreements. So a certificate from one greatly speeds up the other, but does not replace it.
Certification has taken longer than the industry predicted in 2019 to 2021, for reasons that compounded. The powered-lift category was genuinely new, with no regulatory precedent. Distributed electric propulsion brought failure modes that needed new analytical frameworks. Battery fire and thermal runaway certification needed extensive testing.
Supply chain disruption also stretched physical test programmes. The companies that raised billions on 2024 certification timelines were not being fraudulent. The timelines were wrong because nobody had certified this problem before.
The Two Routes That Bypass the Wait
Two mechanisms now let aircraft carry people before a full FAA type certificate exists.
The FAA’s eVTOL Integration Pilot Program. In March 2026 the Department of Transportation selected eight projects across 26 states. Each pairs manufacturers and operators with state partners to test urban air taxi, emergency medical and cargo concepts under real operating conditions. Beta and United Therapeutics, with the Pennsylvania Department of Transportation, flight-tested organ transport from Virginia to Maryland in July. Since then Ampaire has flown a hybrid-electric aircraft across Utah (6 August), Electra flew Manassas to Philadelphia (18 August), Elroy Air made the programme’s first remotely piloted cargo flight in Louisiana (31 August), Joby flew around Dallas-Fort Worth (10 to 14 September), and Joby and Beta opened North Carolina’s trials in September.
These are structured trials with specific route approvals, not open commercial service. But they generate the operational data the certification process needs. They also put aircraft in front of the public.
The UAE’s Restricted Type Certificate pathway. Dubai and Abu Dhabi have built a route aligned with, but faster than, full FAA certification. It allows limited commercial operations without waiting on Washington. Joby holds a six-year exclusive with Dubai’s RTA; Archer is the first manufacturer admitted to Abu Dhabi’s programme.
The UAE has positioned itself to become the world’s first dual-operator eVTOL market. The first commercial electric air taxi flights by a Western manufacturer will very likely happen in the Gulf, not in America or Europe. A regulator there decided to build a pathway rather than wait for one.
What Will an eVTOL Ride Cost?
First-generation commercial flights will be priced as a premium service. Joby has indicated initial pricing of around $3 to $5 per passenger-mile. That is roughly $90 to $150 for a typical urban hop of 20 to 30 miles.
A comparable helicopter charter costs $8 to $15 per mile. So the eVTOL premium over ground transport is real, but so is the discount to helicopters.
The long-term target is $1 to $2 per passenger-mile, once autonomy removes the pilot cost and production scales. At that price it competes with ground transport once time savings are counted. Getting there means solving three constraints at once: certification, battery chemistry and production volume.
City-scale operations need hundreds to thousands of aircraft per metro area. That frequency is what makes an air taxi a transport option rather than a novelty. The first commercial operations will be limited routes in favourable regulatory settings: airport shuttles, high-demand corridors and tourist routes.
When Will You Actually Ride an eVTOL?
If you are in China, you can already ride an EHang EH216 on a sightseeing route. More than a hundred have been flying for two years.
For everyone else, the UAE is first. Joby in Dubai and Archer in Abu Dhabi are both targeting 2026 under restricted type certificates. Neither had launched paying passenger service as of mid-October 2026.
In the United States, eIPP trials are running now. Full commercial passenger service realistically lands in 2028 or later. That means booking a ride in an app, on a certified aircraft, run by a licensed air carrier. It will come once the Part 135 stack is added to a type certificate that does not yet exist.
European service under EASA follows Volocopter’s certification if it holds. The larger vectored-thrust aircraft come behind it.
Scaled autonomous operations with no pilot on board are post-2030, and depend on FAA rulemaking that has not been written.
The popular picture gets one thing wrong. The first certified electric aircraft of this generation will probably not be an air taxi at all. It will be Beta’s CX300, taking off from a runway, carrying cargo and organs.
What to Watch Through 2027
Joby’s for-credit TIA flight testing. FAA test pilots will fly conforming aircraft and file their reports. That is the final data-gathering phase before a type certificate decision. Every delay moves the certificate by the same amount.
Whether Beta certifies the CX300 by the end of 2026. It is targeting the lower regulatory bar and is 89% through certification planning. Success would be the sector’s first hard proof that an electric aircraft can be certified and sold. It would come from the company that skipped vertical takeoff.
Whether the UAE launches actually happen in 2026. Both Joby and Archer have named the year. The Gulf is where the industry’s first commercial revenue will be tested against its first commercial reality.
Whether VoloXPro certifies by the end of 2026. A German ultralight approval would put a certified electric aircraft in customers’ hands from the company that went through insolvency. That is a lower bar than EASA type certification, and still the first of these programmes to deliver one. The separate question is whether VoloCity’s 2027 type certification target holds, now that it sits behind a different product in its own company’s priorities.
Whether the Archer-Boeing deal closes, now that the antitrust waiting period is over, and what Archer then does with Wisk. The only well-funded Western autonomous passenger programme is about to change hands. Its new owner has a more urgent priority.
Vertical’s capital structure. The engineering milestones and the equity value are now separate questions. Watch the drawdown terms, the outcome of the strategic review, and the six months the exchange has given it to lift its share price above $1.
Battery chemistry. Production-ready solid-state cells in the 2028 to 2030 window would transform the economics. They would extend range and cut cost per cycle. Toyota’s involvement in Joby gives that programme first access to whatever its battery research produces.
Vertiport grid connections. Aircraft certification is no longer obviously the long pole. If sites cannot be energised, a certified aircraft has nowhere useful to land.
Sources
- FAA, Electric Vertical Takeoff and Landing and Advanced Air Mobility Integration Pilot Program, Federal Register notice of 16 September 2025 establishing the eIPP; the Department of Transportation’s March 2026 selection of eight projects.
- FAA powered-lift certification under 14 CFR 21.17(b) and the 2024 powered-lift operations rule; EASA’s Special Condition VTOL.
- Company filings and investor pages for the certification and financial figures: Joby second-quarter 2026 results of 5 August 2026, Beta Technologies second-quarter 2026 results, and the Archer, EHang, Eve, Vertical Aerospace and Volocopter statements named in each entry.
- Joby’s second-quarter 10-Q and Texas eIPP flights; Archer’s second-quarter results, Hart-Scott-Rodino announcement and UAE certification programme entry; Skyports on the GCAA certification of the Dubai International vertiport.
- FAA announcements of eIPP flights: Beta, July, Ampaire, Electra, Elroy Air, North Carolina; Beta’s Utah trials.
- Vertical Aerospace’s financing announcement of 20 April 2026 and its Valo assembly centre release of 25 September 2026; Hyundai and Korea Aerospace Industries’ memorandum of 8 May 2026 on Supernal; Boeing’s August 2026 agreement to sell Wisk, Insitu and SkyGrid to Archer.
Coverage
Vertical countersues Archer as court trims Joby lawsuit
Archer now fights its rivals in three forums. Vertical, which wants Midnight blocked, is also under an NYSE warning for trading below $1.
Vertical Aerospace Reviews Options as It Opens Valo Plant
Its cash lasts into August 2027. The first aircraft for certification is due in its new hall at the end of that year.
Volocopter's first product is now a two-seat ultralight
The company that was going to fly the Paris Olympics is certifying an aircraft for flying clubs. Supernal cut 80% of staff. Vertical trades at $0.60.
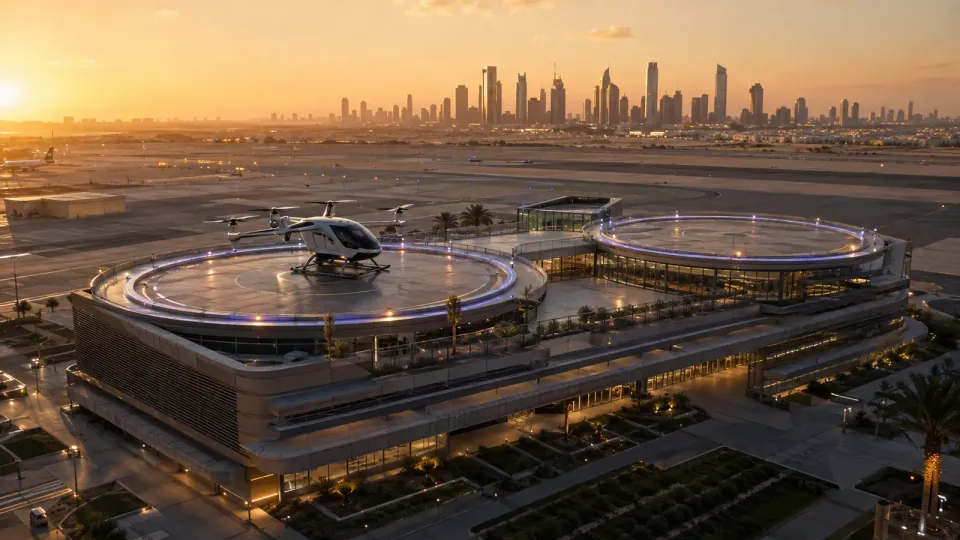
Dubai Certifies the First Purpose-Built Commercial Vertiport
The UAE's GCAA has certified VDX, the Skyports vertiport next to Dubai International, the first purpose-built commercial vertiport to be certified.
Archer Buys Boeing's Wisk, Insitu and SkyGrid in eVTOL Deal
Archer is acquiring Boeing's Wisk Aero, Insitu and SkyGrid, absorbing a rival air taxi programme and a profitable military drone unit in one deal.
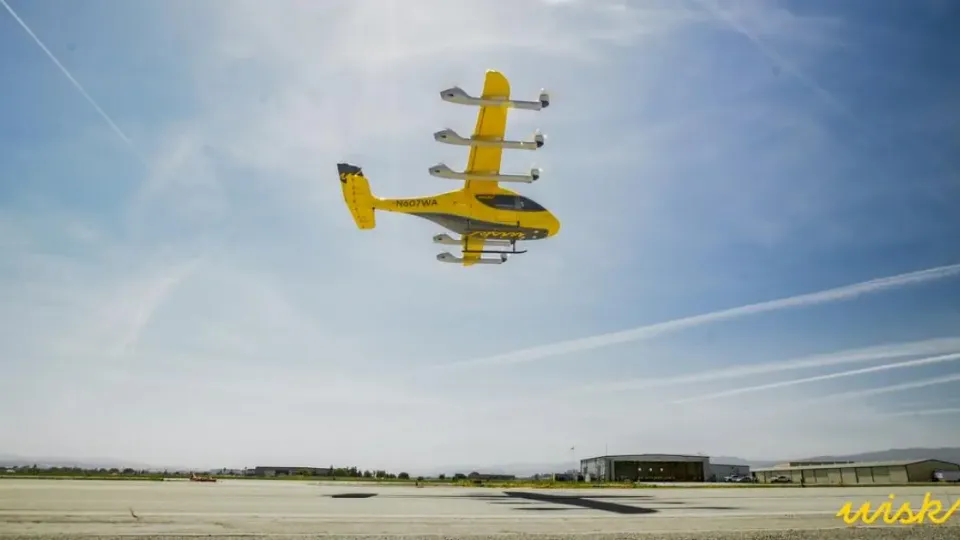
Wisk's Second Gen 6 eVTOL Prototype Completes First Flight
Wisk Aero's second Gen 6 autonomous eVTOL prototype has flown for the first time, joining the original in a California flight test campaign.
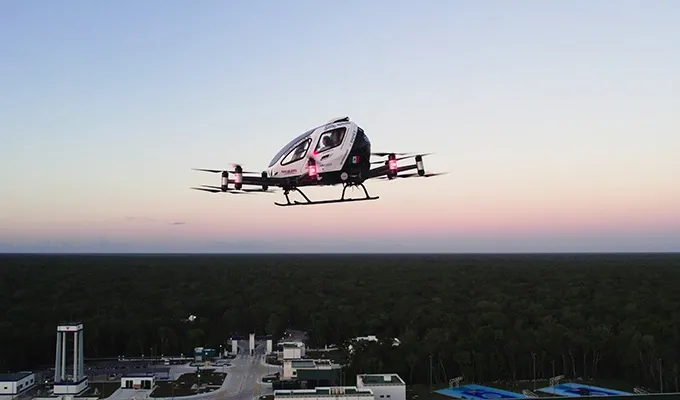
EHang EH216-S Makes First Crewed eVTOL Flights in Mexico
EHang's EH216-S pilotless eVTOL completed its first people-carrying flights in Mexico and Latin America at the FAMEX Tulum Air Show 2026.
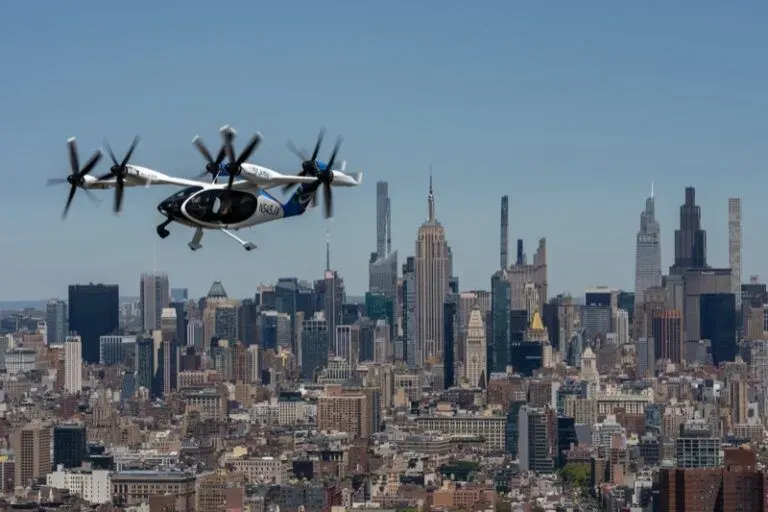
Joby Aviation Flies eVTOL Over New York City
Joby Aviation flew its S4 eVTOL between JFK and Manhattan heliports in New York City's first electric air taxi flights.
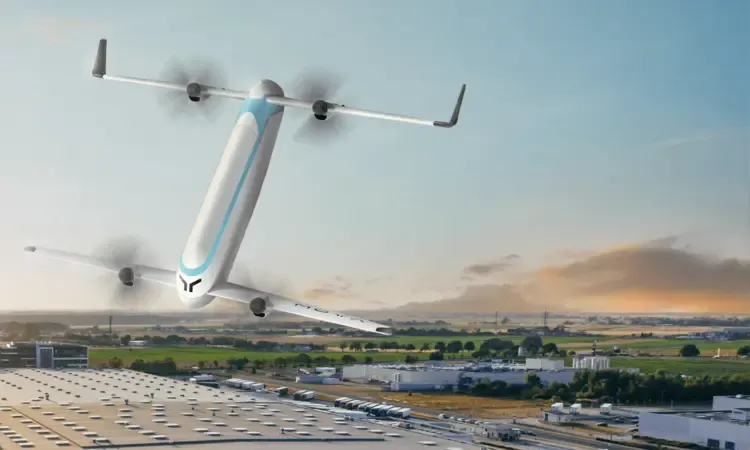
Speedbird and Moya Aero Partner on eVTOL Logistics
Speedbird Aero and Moya Aero have signed an MoU to explore combining Moya's tilt-body eVTOL with Speedbird's BVLOS drone logistics operations.
Archer and Joby: Who Gets FAA Certification First in 2026?
Archer Aviation and Joby Aviation are both targeting FAA type certification in 2026. Here's where each program stands and what's left to clear.
FAA Launches eVTOL Pilot Program Across 26 States
The FAA has selected eight projects for its eVTOL Integration Pilot Program, with operations expected to begin by summer 2026 across 26 states.
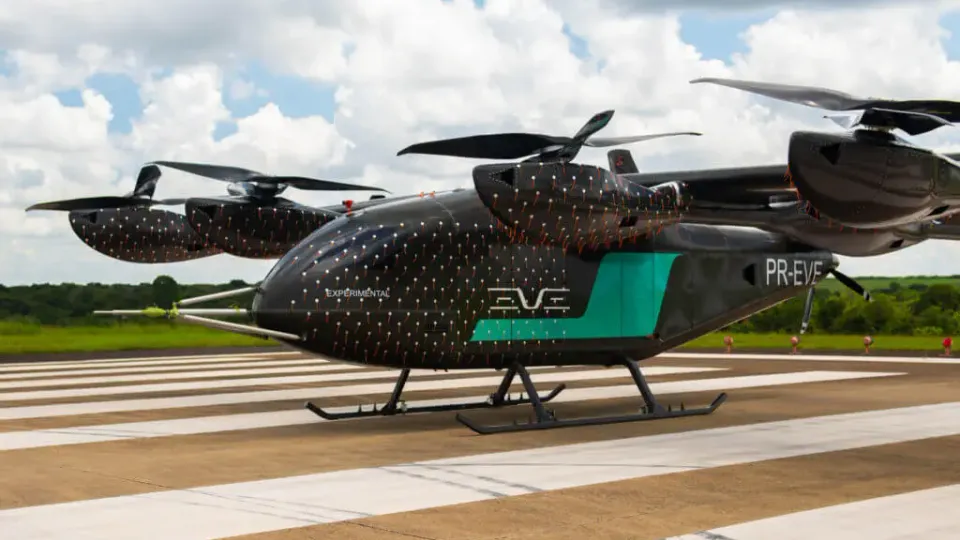
Eve Air Mobility Targets Helicopter Operators in 2026
Eve Air Mobility arrives at VERTICON 2026 with 2,700 eVTOL orders and near-daily test flights targeting helicopter fleets.
Japan's AAM Roadmap Is Built to Actually Work
Japan's advanced air mobility plan phases infrastructure, regulation, and public trust alongside aircraft development to 2030.
Companies
Joby Aviation
US eVTOL company developing a five-seat electric air taxi, the furthest along in FAA type certification among civilian eVTOL manufacturers.
United States
Archer Aviation
US eVTOL company developing the Midnight air taxi, now acquiring Boeing's Wisk Aero, Insitu and SkyGrid to add autonomy and defense manufacturing.
United States
Vertical Aerospace
UK eVTOL developer building the Valo, a four-passenger electric air taxi targeting UK type certification in 2029, now reviewing strategic alternatives.
United Kingdom
Wisk Aero
US developer of an autonomous four-seat air taxi, wholly owned by Boeing and being sold to Archer Aviation in a deal expected to close by end-2026.
United States
Boeing
Boeing is a US aerospace manufacturer with commercial-airplane, defense and space, and fleet-services businesses.
United States
EHang
Chinese autonomous aerial vehicle company with a type-certified EH216-S passenger eVTOL and related aerial-mobility products.
China
Bell Textron
US rotorcraft manufacturer and advanced air mobility developer, making military helicopters, tiltrotors, and autonomous cargo drone platforms.
United States
BETA Technologies
Vermont-based electric aircraft maker, listed on the NYSE, building the ALIA CX300 and A250 and the charging network they run on.
United States
Contracts
U.S. Navy
Boeing
Not-to-exceed undefinitized modification for three MQ-25A Stingray low-rate initial production Lot 1…
U.S. Navy
Boeing
Engineering and integration of an updated radio-frequency blanker and encrypted mass storage for the…
U.S. Army
Elroy Air
SBIR Phase III contract to develop an autonomous Group 4 hybrid vertical take-off cargo drone for…
U.S. Navy
Boeing
Engineering and hardware for laboratory testing to certify the MQ-25A mission management computer's…
U.S. Navy
Boeing
Structural repair manual procedures for the MQ-25A test aircraft; order N0001926F0221.